Documenting Front Range Hail Damage Before You Invoke Appraisal
Hail claims are won or lost on documentation. Here’s what to capture — on the roof and off it — before anyone argues about price.
Independent property claim appraisal · Statewide
When your insurer accepts the claim but the payment won’t rebuild what you lost, Colorado Insurance Appraiser prepares an independent, line-by-line valuation and carries it through the appraisal process written into your policy.
Retained by you — never by the carrier
What we do
Most disputed claims in this state aren’t denials. They’re short payments: a roof priced as a repair when the shingles are discontinued, a hail claim that skipped the gutters and window wraps, a wildfire smoke loss that cleaned surfaces nobody tested. Colorado Insurance Appraiser works in that gap between “covered” and “paid in full.”
Services
Eleven services built around a single job: a valuation of your loss that holds up in front of the other appraiser and, if it comes to that, an umpire.
Not sure where to start? Most files begin with a carrier estimate review.
Compare all services Appraisal Clause RepresentationWe serve as the appraiser you name once either side invokes your policy’s appraisal provision.
 Homeowner Claim AppraisalIndependent valuation for houses, condos and townhomes when the carrier’s estimate won’t cover the repair.
 Commercial & HOA Claim AppraisalLarge-loss appraisal for associations, multifamily, retail, office, industrial and church properties.
 Hail & Roof Damage AppraisalRoof, gutter, siding and window hail claims — the most common dispute along the Front Range.
 Wind & Tornado Claim AppraisalDownslope windstorms, plains tornadoes and straight-line winds that lift shingles and tear siding.
 Snow Load & Ice Dam AppraisalWinter claims: roof collapse, ice dams, frozen pipes and water damage in mountain and metro homes.
 Water & Burst Pipe AppraisalSudden water losses from burst pipes, failed supply lines and appliances, including mold-related scope.
 Fire & Smoke Loss AppraisalStructure fires and smoke contamination: cleaning versus replacement, odor, soot and contents.
 Wildfire Claim AppraisalTotal losses and smoke-exposed homes in the wildland-urban interface — Colorado’s signature disaster.
 Carrier Estimate ReviewA line-by-line review of the insurer’s estimate, showing what’s missing and whether appraisal is worth it.
 Umpire & Neutral ServicesNeutral umpire service for appraisal panels across Colorado, with no ties to either side.
Statewide knowledge
A hailstorm in Aurora, a frozen pipe in a Vail condo and a wildfire on the Western Slope produce very different estimates. A Colorado Insurance Appraiser has to know how each region’s weather shows up on a building — and in the carrier’s numbers.
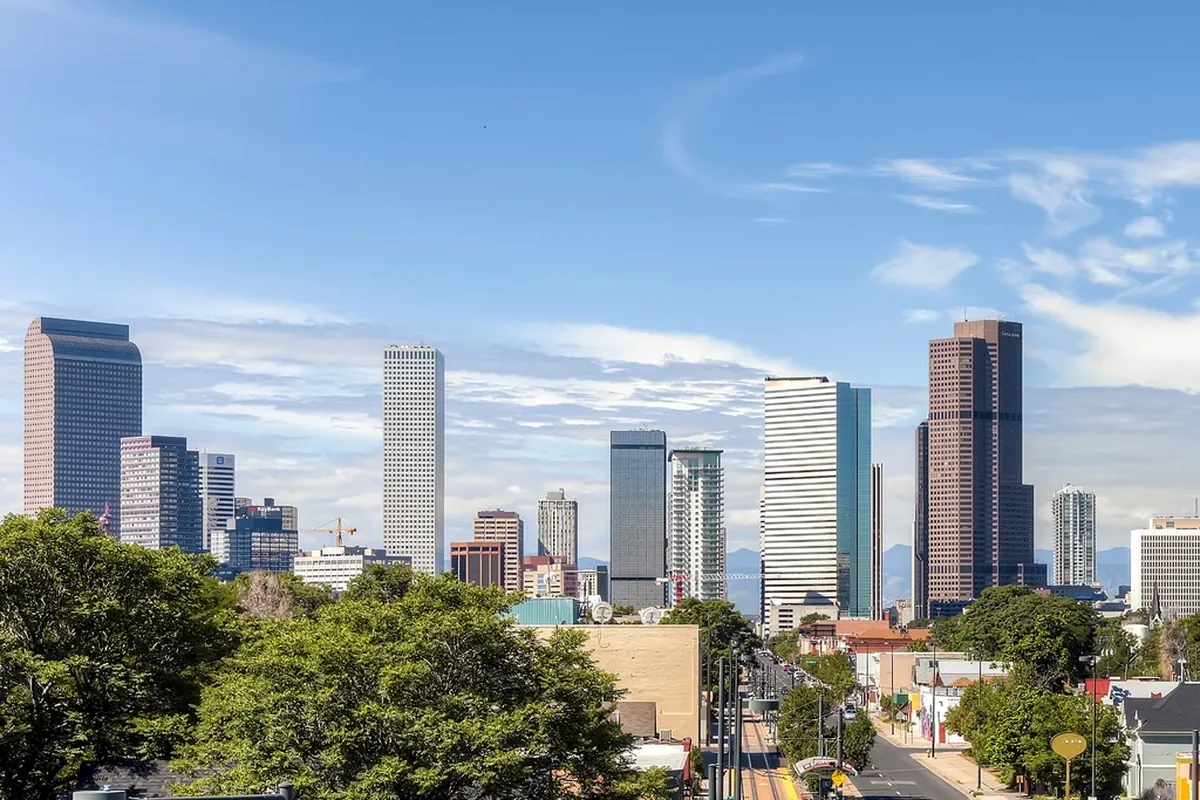
Denver · Colorado Springs · Fort Collins
Most of the state’s population lives along the I-25 corridor, and so do most of its hail claims. Storms that form over the foothills on summer afternoons drift east over Jefferson, Denver, Arapahoe, Douglas, El Paso, Larimer and Weld counties, often hitting the same neighborhoods year after year.
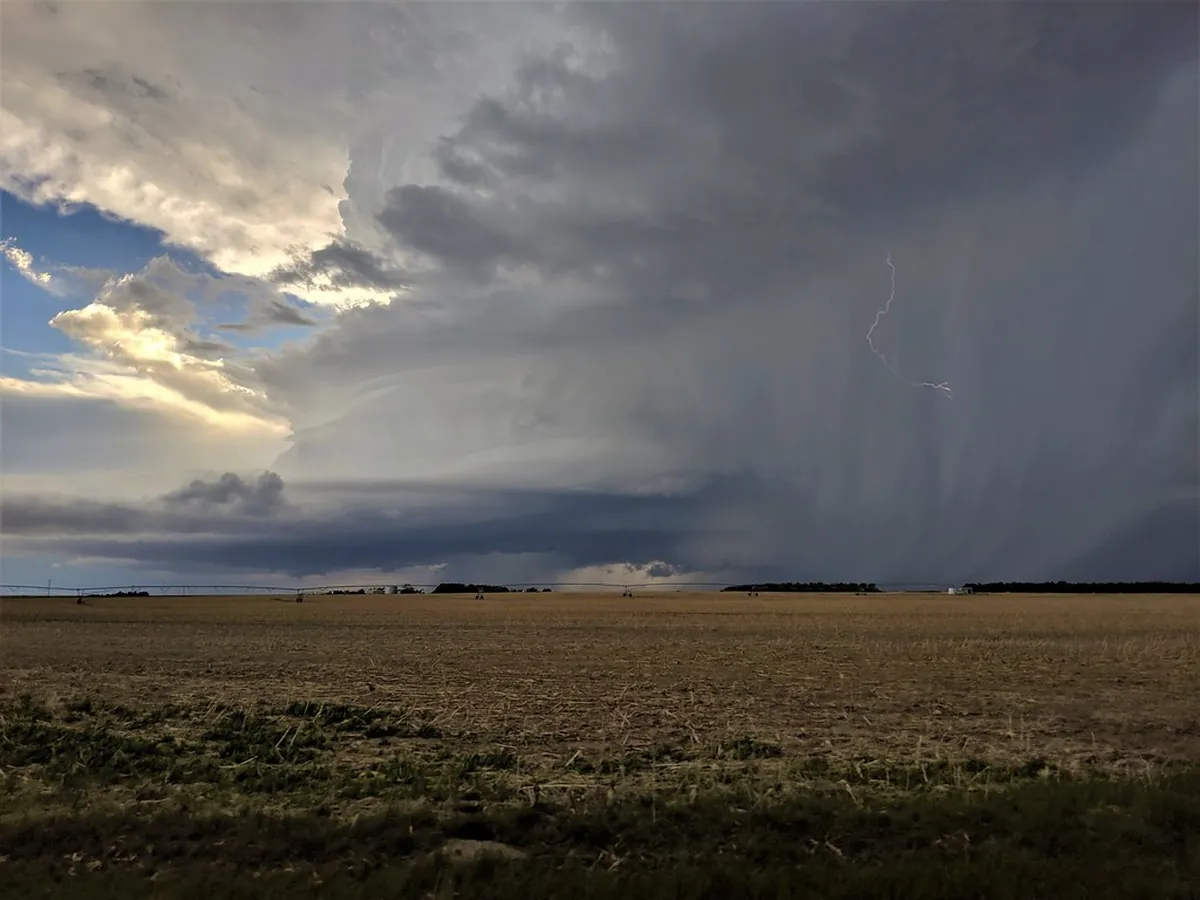
Greeley · Sterling · Lamar
East of the urban corridor, open farm country produces the state’s tornadoes and some of its largest hailstones. Claims often blend a farmhouse, machine sheds, grain bins and fencing under one policy, with long drives between adjusters.
Summit · Eagle · Pitkin · Grand
High-country claims follow the calendar: heavy snow on roofs in winter, burst pipes in unoccupied second homes, and wildfire threat in summer and fall. Remote sites, short building seasons and resort-area labor costs all push repair prices above metro levels.
Grand Junction · Montrose · Glenwood Springs
Mesa, Delta, Montrose and Garfield counties see strong canyon winds, summer fire on the surrounding mesas and occasional damaging hail. Contractor availability and material delivery from the Front Range can stretch repair timelines.
Pueblo · Durango · Trinidad · Alamosa
From the Pueblo area to La Plata County and the San Luis Valley, the south mixes high-desert hail and wind with forest fire risk around Durango and the Sangre de Cristo foothills.
Hail Alley
Forecasters use the name for the high plains where the country’s most frequent large hail falls, and metro Denver sits squarely inside it. The May 8, 2017 storm that battered the west metro is often cited as the costliest insured event in state history, and a 4.83-inch stone that fell near Bethune in 2019 set the state record.
For a Colorado Insurance Appraiser, that history matters: repeat storms create arguments about old versus new damage, discontinued shingles and whether a roof can really be repaired.
Hail & roof appraisalThe process
The appraisal clause turns an open-ended argument into a defined process with a binding result on the amount of loss. Here is the path, start to finish.
We read the policy, the carrier’s estimate and your photos, then tell you plainly whether appraisal fits.
An on-site inspection and a line-item estimate priced for your part of Colorado.
Appraisal is invoked in writing and we’re named as your appraiser within the policy’s time frame.
We work through the estimates with the carrier’s appraiser. Most disputes narrow sharply here.
Remaining items go to a neutral umpire. Two signatures set the amount of loss.
Free & private
Check the carrier’s math before you pick up the phone. Every tool runs in your browser; nothing you type is stored or sent.
 Calculator
 Calculator
 CalculatorCalculator
 Planner
 ChecklistReference
Service areas
We take files in every county. These are the cities where Colorado Insurance Appraiser handles claims most often, each with its own storm history and housing mix.
DenverCity & County of Denver Colorado SpringsEl Paso County
 AuroraArapahoe, Adams & Douglas Counties
 Fort CollinsLarimer County
 BoulderBoulder County
 LakewoodJefferson County
 PuebloPueblo CountyGreeleyWeld County
 LongmontBoulder & Weld Counties
 Castle RockDouglas CountyGrand JunctionMesa CountyDurangoLa Plata County
Choosing help
Each solves a different problem. Picking the right one first saves time and fees, and Colorado Insurance Appraiser will point you elsewhere when appraisal isn’t the right fit.
Values the amount of loss
Handles the whole claim
Handles legal disputes
FAQ
Straight answers about how appraisal works, what it costs and when it’s the wrong move.
A Colorado Insurance Appraiser values property damage when you and your insurer agree the loss is covered but disagree on what it costs. Once appraisal is invoked, we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, if needed, present unresolved items to a neutral umpire.
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question — the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
Usually after the carrier has issued its estimate and you have a contractor’s number that is meaningfully higher. Call sooner if a deadline in your policy or a letter from the insurer is approaching.
On the amount of loss, generally yes, once two of the three panel members sign. Appraisal doesn’t decide coverage questions, which is why the file should be well documented before anyone invokes it.
Each side pays its own appraiser and typically shares the umpire’s fee. We put our fee in writing before work starts, and the first conversation is free.
Yes. We work in all 64 counties, from the Denver metro and Colorado Springs to Grand Junction, Durango, the mountain resort towns and the Eastern Plains.
Guides
Practical guides from Colorado Insurance Appraiser on hail documentation, wildfire claims, deductibles and reading an estimate.
Hail claims are won or lost on documentation. Here’s what to capture — on the roof and off it — before anyone argues about price.
A wildfire total loss is a marathon. Here’s how rebuild cost, contents and living expenses usually play out — and where appraisal can help.
A 2% deductible sounds small until you do the math. Here’s how percentage wind/hail deductibles work and why they matter in a dispute.
A short review by Colorado Insurance Appraiser now can keep you from accepting a settlement that won’t cover the repair.
Start with a conversation
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing — no pressure, no obligation.